A budget can be disrupted without being useless. Overspending, a higher-than-expected bill, an urgent repair, a missed estimate, or a change in income can make the original plan inaccurate. The practical question is not whether the month still matches the first version of the budget. It is what the best plan is from this point forward.
That shift matters because many people respond to a disrupted budget by avoiding it. Once the original numbers no longer work, they stop checking balances, postpone decisions, and wait for the next month to start over. A reset approach treats adjustment as part of budgeting rather than evidence that the budget failed.
Start With the Current Reality, Not the Original Plan
Suppose you planned the month carefully and then faced a car repair, a medical cost, an unusually high utility bill, or simply more flexible spending than you intended. The money already spent cannot be moved back into the account. Reconstructing what you “should” have done may explain what happened, but it does not solve the next decision.
A reset starts by establishing the present position. What money is available now? What income is still expected? Which obligations must still be paid before the next reset point? Which priorities can remain protected, and which may need to change temporarily?
This is a forward-looking process. The past is useful only insofar as it helps you make the remaining plan more realistic.
Use Four Questions to Rebuild the Rest of the Month
The reset method described in Marcus Weston’s The 1-Hour Budget can be reduced to four practical questions.
1. What comes in from here?
List the income you still expect before the next planning period. If income is variable, use a conservative estimate rather than assuming the highest possible amount.
2. What must go out from here?
Identify the obligations that still need to be covered: housing, utilities, insurance, transport, minimum debt payments, childcare, or other commitments. Focus on what remains, not what has already been paid.
3. What can still be protected?
Review savings, extra debt payments, annual-bill funds, or other priorities. Some may stay unchanged. Others may need a temporary reduction. The useful question is not whether the original amount was ideal, but what amount is realistic now.
4. What is available for flexible spending now?
After the remaining obligations and protected priorities are accounted for, calculate what is actually available for groceries, fuel, household needs, personal spending, and other flexible expenses.
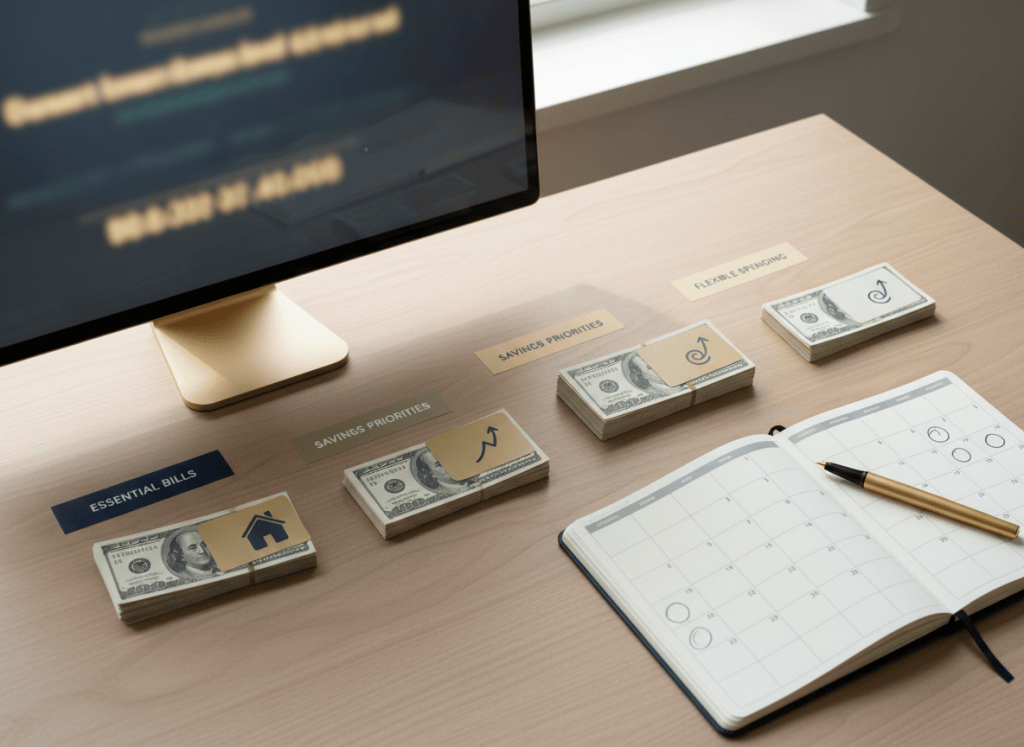
Do Not Protect Every Goal at the Expense of Basic Stability
A common problem during a reset is trying to preserve every original target even though the financial situation has changed. If an unexpected cost has reduced the available money, forcing the original savings or extra debt-payment target may leave too little for ordinary necessities.
That does not mean future goals no longer matter. It means priorities have to operate inside current reality. A temporary reduction can be more sustainable than moving money into savings and then immediately pulling it back out because the rest of the plan became impossible.
Likewise, a reset should not automatically eliminate all flexible spending. A plan that assumes no groceries beyond the bare minimum, no transportation variation, and no ordinary personal needs may look disciplined on paper but fail quickly in practice.
Convert the New Flexible Amount Into a Shorter Time Horizon
When the month has already changed, a full-month number may no longer be helpful. Divide the remaining flexible money across the weeks or days that remain until the next planning point.
A shorter time horizon makes the reset easier to use. If two weeks remain, you can work with two weekly guide numbers rather than comparing every purchase with a monthly target that is no longer relevant.
This is closely related to the four-number approach discussed in How to Budget Without Spreadsheets: A Four-Number System for People Who Feel Overwhelmed by Money. The aim is to keep the number of decisions manageable while preserving enough information to make good choices.
Separate a One-Time Disruption From a Structural Problem
Not every budget disruption means the entire system is unrealistic. A one-time repair or unusual bill may require only a temporary reset. But repeated overspending in the same area can signal that the original estimate is too low.
For example, if groceries exceed the planned amount month after month, the useful response may be to change the grocery estimate rather than repeatedly promising to spend an amount that does not match actual household needs. If fixed obligations consistently leave almost no flexible room, the problem may be structural rather than behavioral.
The same applies to irregular expenses. An annual fee, seasonal cost, school expense, or routine vehicle maintenance may feel unexpected when it arrives, even though its general existence was predictable. Future versions of the budget can move such costs into protected priorities before they arrive.
Avoid Turning the Reset Into a Punishment Plan
After overspending, it is tempting to respond with an extreme correction: no discretionary purchases, unrealistic grocery limits, aggressive transfers, or a promise to track every cent. That reaction may feel decisive, but it often creates another plan that is difficult to maintain.
A more useful reset is specific. Reduce one area. Delay one optional purchase. Revise one protected amount. Identify one upcoming expense that needs a place in the plan. The goal is to restore visibility and control, not to make the rest of the month unpleasant enough to compensate for what happened earlier.
A Ten-Minute Reset Can Be Enough
If avoidance is the biggest obstacle, keep the reset short. Open the relevant accounts, write down the current available money, list the remaining obligations, decide what can still be protected, and calculate a new flexible-spending guide. Then choose one adjustment and stop.
- Look at the current numbers.
- Identify what changed.
- Protect what is still realistic.
- Set a new spending boundary.
- Continue from there.
This process does not guarantee a particular financial outcome, and complex debt or financial situations may require individualized professional advice. Its purpose is narrower: to make it easier to re-enter the plan after real life has changed the numbers.
A Budget Is a Living Plan, Not a Scorecard
The most useful budget is not necessarily the one that remains unchanged all month. It is the one that keeps helping you make decisions after conditions change.
That philosophy runs through Marcus Weston’s The 1-Hour Budget: look at what is true now, adjust the plan, and continue rather than abandoning the system because one part did not go as expected. Readers interested in his broader practical approach to money habits can visit the Marcus Weston author page and read Why Wealth Is More Than a Number: Building Financial Confidence from Self-Worth, Not Fear.

